Help to Buy rises to €35,000: what it means for self-builders
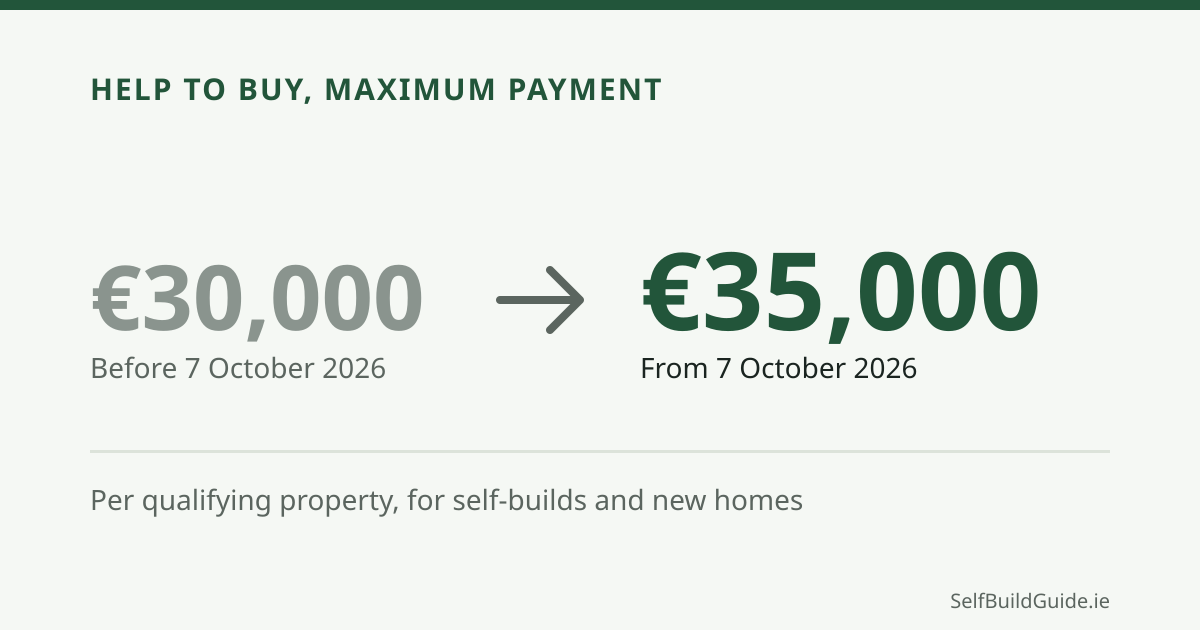
The Help to Buy cap rose by €5,000, to €35,000, from 7 October 2026. You only get the full rise if your home's valuation and the tax you have paid qualify.
In brief
- The maximum Help to Buy payment is now €35,000 per qualifying property, up from €30,000, for applications from 7 October 2026 to 31 December 2029.
- Other conditions are unchanged, including the €500,000 limit on the approved valuation, the 10% rule and the four-year tax look-back.
- You only gain if both the 10% limit (an approved valuation over €300,000) and your tax paid (over €30,000 across four years) exceed the old cap.
- For a self-build, the qualifying event is your first mortgage drawdown, not the day you sign a building contract.
You can claim up to €35,000 through Help to Buy (HTB) for a qualifying self-build, following the €5,000 increase announced in Budget 2027 on 6 October 2026. The higher cap helps only if your qualifying tax paid and 10% of the approved valuation both exceed the old €30,000 limit.
When does the higher limit apply?
The €35,000 cap applies to qualifying applications from 7 October 2026 to 31 December 2029. For a self-build, your first mortgage drawdown must also fall within that period. The earlier €30,000 cap covered applications and qualifying events from 23 July 2020 to 6 October 2026.
The cap applies per property, however many people are named on the mortgage. Confirm your claim with Revenue before relying on the full amount in a contract or borrowing decision. Revenue is applying the higher cap in its current guidance; confirmation of your entitlement is still necessary before committing money.
What are the other conditions?
The higher cap leaves the other conditions unchanged:
- The approved valuation of your self-build must not exceed €500,000.
- Your refund is the lowest of the cap, 10% of the approved valuation, and the income tax and Deposit Interest Retention Tax (DIRT) you paid in the four years before applying. Universal Social Charge (USC) and Pay Related Social Insurance (PRSI) do not count.
- You must be a first-time buyer, have a qualifying mortgage of at least 70% of the approved valuation, and live in the home for five years.
Check the full Help to Buy eligibility and claim process before applying.
How much extra could you receive?
Help to Buy refunds tax you have already paid. To gain from the increase, both of these must be true:
- 10% of your approved valuation is more than €30,000. That means a valuation above €300,000.
- You paid more than €30,000 in income tax and DIRT in the four years before applying.
Your increase is the smallest of €5,000, the amount by which 10% of your valuation exceeds €30,000, and your qualifying tax above €30,000. These hypothetical examples show the calculation; they are not Revenue assessments:
| Approved valuation | Tax and DIRT paid (4 years) | Refund at €30,000 cap | Refund at €35,000 cap | Gain |
|---|---|---|---|---|
| €280,000 | €45,000 | €28,000 | €28,000 | €0 |
| €340,000 | €45,000 | €30,000 | €34,000 | €4,000 |
| €400,000 | €32,000 | €30,000 | €32,000 | €2,000 |
| €400,000 | €50,000 | €30,000 | €35,000 | €5,000 |
| €400,000 | €18,000 | €18,000 | €18,000 | €0 |
At a €280,000 valuation, the 10% rule limits the refund to €28,000. At €18,000 of qualifying tax, the tax paid limits it to €18,000. In either case, raising the cap makes no difference.
Check the types of tax on your payslips rather than adding up every deduction. A couple on modest Pay As You Earn (PAYE) incomes may not have €30,000 in qualifying tax between them, particularly if a large part of their deductions is USC and PRSI.
What if you have already applied?
For a self-build, the qualifying event is your first mortgage drawdown, not signing a building contract. Both the application dates and that first drawdown matter. If you have already applied or are approaching drawdown, ask Revenue how the change applies to your claim before assuming you will receive the higher amount.
Agree the timing with your lender and solicitor so the refund fits your staged mortgage payments. A higher entitlement does not make the refund available before the claim requirements are met.
What should you do now?
- Ask your lender for the approved valuation and compare it with the €300,000 and €500,000 thresholds.
- Check your income tax and DIRT paid across the previous four years. Revenue provides an indicative maximum when you start an application.
- Confirm the application and first-drawdown dates with Revenue if your claim spans the change.
- Budget for the amount Revenue confirms for you, rather than assuming the full €35,000.
Sources
Last reviewed 6 October 2026. Rules and figures change, so confirm anything important with the source before you rely on it.
- Help to Buy (HTB): how much can you claimRevenue
- Help to Buy (HTB): who can claimRevenue
- Housing and property measures (Budget 2027)Chartered Accountants Ireland
- Budget 2027 main points: everything you need to knowThe Irish Times
News articles describe what was announced or published on the date shown. They are general information, not financial, tax or legal advice, and measures announced in a Budget may change before they become law.