ECB rate rises to 2.5%: what it means for your self-build mortgage
The ECB raised its deposit rate twice in 2026, to 2.50%. What that changes for a self-build mortgage drawn in stages, and what it doesn't.
In brief
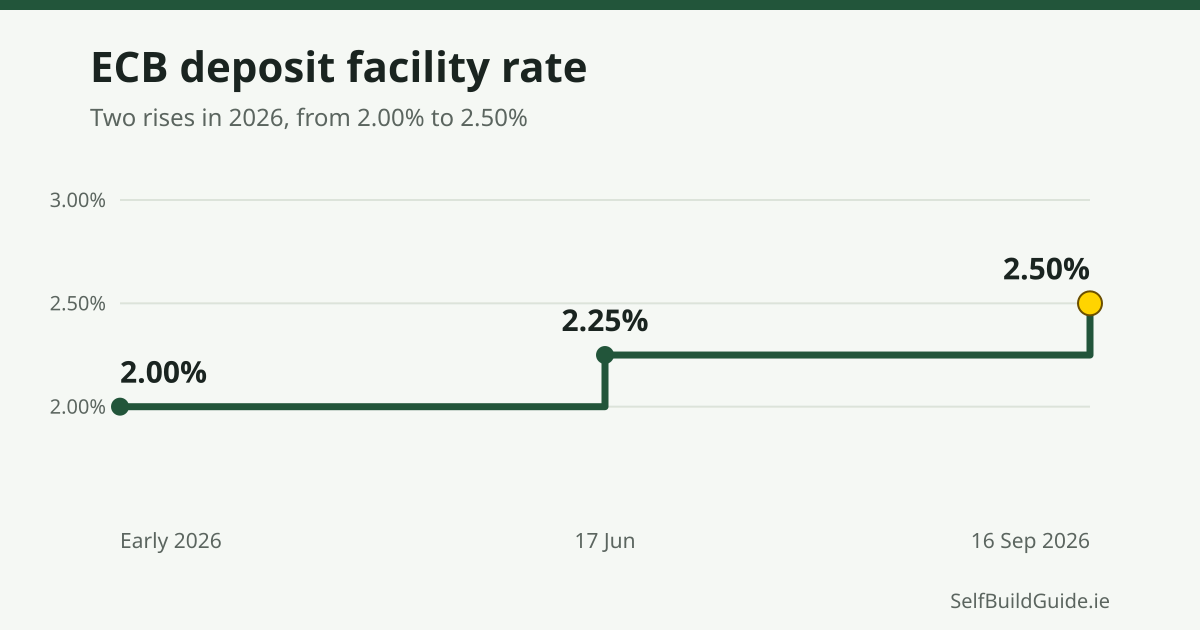
- The ECB deposit facility rate rose from 2.00% to 2.25% on 17 June 2026 and to 2.50% on 16 September 2026.
- A tracker mortgage follows ECB rate changes. A fixed rate does not change until the fixed period ends.
- With a staged drawdown you pay interest only on what you have drawn, so a rise costs less early in the build than at the end.
- Ask your lender in writing which rate applies to each drawdown and when the fixed period ends.
The European Central Bank (ECB) has raised its deposit facility rate twice this year. The rate was 2.00% until 16 June 2026. It rose to 2.25% on 17 June and to 2.50% on 16 September, following the Governing Council’s decision of 10 September. Whether that changes your repayments depends on the type of mortgage you have.
Does the ECB rate change affect your mortgage?
It depends on the rate type. A tracker mortgage moves with ECB rates, so your rate changes when the ECB’s does. A fixed rate stays the same until the fixed period ends, then moves to the lender’s then-current rate. A variable rate moves when your lender decides, which is often after an ECB change but not always by the same amount.
Check your offer letter for which one you have. If you have not yet drawn down, ask which rate applies to each stage payment, because a lender may fix the rate for the whole loan or for each drawdown separately.
How does a rise affect a staged drawdown?
A self-build mortgage is usually released in stages as the build progresses. Interest is charged only on the amount drawn so far. A rise therefore costs little while the balance is small, and more as later stages are released. See how staged drawdown works and how to plan the interest you pay during the build.
A rise of 0.25 percentage points adds about €25 a year in interest per €10,000 borrowed. On a fully drawn €300,000 loan, that is about €750 a year, or €62 a month. Your lender’s actual rate change may differ, so use their figure when you budget.
What should you do now?
- If you are on a tracker or variable rate, rework your build-period budget with a higher rate than today’s. Interest during the build comes on top of the rent or mortgage you already pay.
- If you are about to choose a rate, compare lenders on both the rate and what happens when the fixed period ends. See how lenders compare.
- If your mortgage approval is close to expiring, ask the lender which rate it assumed and whether it will be reassessed.
This article reports the ECB’s rate changes. It is not a forecast. The ECB sets policy at each meeting, and your lender sets your mortgage rate. For the full picture of borrowing for a self-build, see the self-build mortgage guide.
Sources
Last reviewed 16 September 2026. Rules and figures change, so confirm anything important with the source before you rely on it.
- Key ECB interest ratesEuropean Central Bank
- ECB data portal: deposit facility rate (daily series)European Central Bank
News articles describe what was announced or published on the date shown. They are general information, not financial, tax or legal advice, and measures announced in a Budget may change before they become law.